By Charles Obiajulu Ugwu PhD
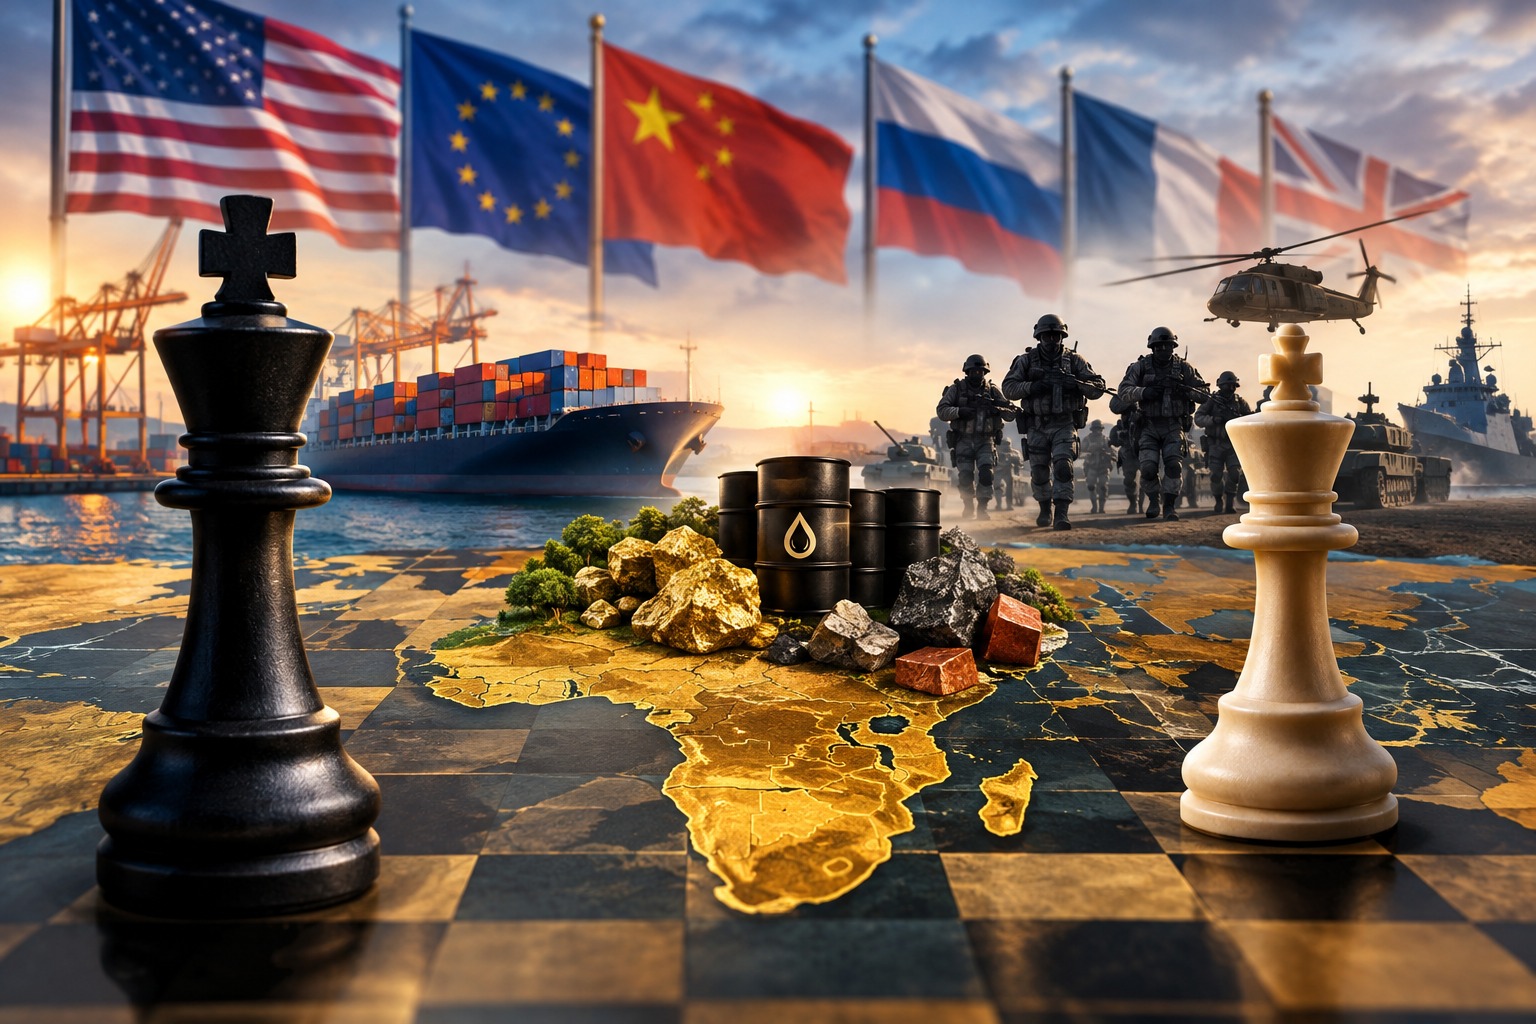
There is something unsettlingly familiar about the attention Africa is now receiving. The vocabulary has been refined and the cast has multiplied, but the encounter keeps its old shape. Nobody needs to draw borders on a map any more. The contest arrives as investment, infrastructure, strategic partnership, supply-chain resilience, energy security, technology cooperation and development finance, each phrase respectable and each defensible on its own terms. Beneath them sits an older question in new clothes: who gets to determine the value of what Africa possesses?
The question is pressing because the world’s economic transition now leans on the continent’s geography, geology and demography as never before. The energy transition consumes minerals in vast quantities. Digitalisation demands physical infrastructure on a scale few anticipated. Artificial intelligence, so weightless on a screen, depends on electricity, computing capacity, cooling and transmission, and behind those on a long chain of materials and components. Advanced manufacturing needs secure access to inputs concentrated in a handful of places, at the very moment governments and corporations are trying to reduce their exposure to fragile and over-concentrated supply chains. Africa sits at the crossing of many of these needs.
The temptation is to announce that Africa’s moment has arrived. That conclusion is premature, and the reason it is premature is the argument of this essay. Strategic importance is not strategic power. A country can hold an asset the world urgently needs and still exercise remarkably little influence over the economic system that has grown around it. Whether the present moment becomes another cycle of extraction or the beginning of genuine industrial transformation will turn on that distinction.
The first Scramble was a contest over territory. The second is a contest over the systems through which resources become value: processing, manufacturing, infrastructure, finance, technology, logistics, energy, data and access to markets. It is no longer settled by what lies beneath African soil. It is settled by what can be built around it.
Two Stories, One Mistake
Two stories dominate the public conversation, and they seem to be opposites. The first is a story of arrival. The world needs cobalt, copper, lithium and graphite, Africa has them, and so Africa’s hour has struck, with demand doing the work that policy has so far failed to do. The second is a story of renewed plunder. Foreign powers and corporations are back for the minerals, the terms will be unfavourable, and Africa will once more be acted upon rather than act. A third story, newer, borrows from both: that the whole affair is a duel between China and the West, with African states as the ground on which two giants wrestle.
Each contains something true, and each rests on the same concealed premise. All three assume that value sits in the ground, waiting to be found, and that the only live question is who holds the shovel and who holds the cheque. The optimist counts the deposits. The pessimist counts the buyers. Neither asks the question on which the outcome depends, which is who commands the chain that turns rock into capability.
Value does not lie in the rock. It is made, step by step, through refining, engineering, finance, standards and markets, and whoever commands those steps collects most of the result. Read this way, Africa is neither prize nor victim. It is a party to a negotiation whose outcome will be set by capability, and by the quality of the bargaining that capability makes possible.
From Territory to Systems
The nineteenth-century scramble demanded physical occupation because territory was itself the principal instrument of power. Colonial administrations needed control of land, people, ports and resources, and they built railways to carry productive hinterlands to coastal points of export. The economic geography of the continent was shaped, accordingly, around extraction.
Today’s world does not require possession. A state need not own another country’s territory to become decisive within its economy. Long-term supply agreements secure minerals. Infrastructure finance bends the direction of trade. Processing capacity creates dependence. Technology decides who captures the richest stretch of a supply chain, financial institutions decide which projects become commercially viable, standards decide which products may enter global markets, and ports and railways decide where commodities flow. Power has become more mobile, and because it is more mobile it is often harder to see.
None of this licenses the lazy claim that the nineteenth century is returning in modern dress. The contemporary system is structurally different. African governments are sovereign and African firms have greater agency. Capital arrives from many more sources, and China, India, the Gulf states, Europe, the United States, Japan and South Korea each pursue different interests across the continent. The resemblance lies elsewhere. Once again Africa holds materials that external economies regard as strategic. The difference is that the decisive contest now takes place above the mine and beyond the port.
The Weight Beneath the Weightless
The green and digital transformation has produced a paradox. The more loudly the world speaks of leaving fossil fuels for a cleaner, smarter and more digital economy, the more it depends on physical matter. Electric vehicles need batteries, batteries need minerals, and electricity networks need copper. Wind turbines, solar systems, electronics, defence technologies and advanced manufacturing all rest on intricate mineral supply chains. The so-called weightless economy has a very heavy foundation, and Africa occupies a significant part of it.
The African Development Bank estimates that the continent holds about 30 percent of the world’s critical-mineral reserves, among them cobalt, lithium, graphite, rare earths, platinum-group metals, copper, manganese and nickel. The Democratic Republic of Congo shows how concentrated that significance can be. UN Trade and Development reports that the country accounted for 74 percent of global cobalt mine production in 2025.
Figures like these invite a simple conclusion, and the simple conclusion is wrong. To hold three-quarters of a mineral’s mine output is not to hold three-quarters of the economic power that mineral generates. The mine is where value begins. It is rarely where value is decided.
Where Value Is Made
The raw mineral has a price. The processed material has another, the manufactured component a third, and the technology built around that component a fourth. Intellectual property, specialised equipment, standards, finance and distribution may capture more again. The strategic question therefore shifts from who has the mineral to who controls the chain through which the mineral becomes something worth having. UNCTAD’s recent analysis shows the pattern plainly: extraction is geographically spread, but refining and processing are heavily concentrated, with China holding dominant positions in several critical-mineral chains. That is not an indictment of China. It is a description of where economic power resides.
Africa can mine cobalt without making batteries. It can dig lithium without building the technologies that consume lithium, export copper without constructing the electrical systems that turn copper into industrial capability, and hold graphite without touching the downstream applications that make graphite strategic. Geological abundance can coexist with economic dependence. Commodity-producing societies from the Gulf to the Andes to Southeast Asia have lived some version of this, with very different results. Africa’s history nevertheless gives the problem particular weight, because the continent has repeatedly supplied raw materials to external industrial systems without acquiring a proportionate share of the productive capability those systems create.
The right question, then, is not whether Africa should mine. It is whether Africa can move intelligently up the chain, into activities its economics can sustain. The qualifier matters. Local processing is not rational merely because it is politically attractive. Some stages demand enormous energy, specialised technology or scales that make regional or international production more efficient, and a policy that ignores this will spend scarce capital on showpieces. The sophisticated question is not how to keep everything at home. It is which parts of the value chain Africa can competitively own, and which capabilities it must build to capture them. That is where a serious industrial strategy begins.
Infrastructure changes its meaning once the argument is framed this way. A mine is worth little if its output cannot reach a market at competitive cost. A refinery cannot run without dependable power and transport, a factory cannot survive without suppliers, logistics and customers, and a regional industrial economy cannot form where borders impose prohibitive friction on the movement of goods. Infrastructure does more than connect places. It determines which economic possibilities become viable.
The Lobito Corridor shows the point. It ties the copper and cobalt districts of the DRC, and in time Zambia, to Angola’s Atlantic coast along a railway of roughly 1,300 kilometres, and it has lately begun to move from a set of national projects toward a coordinated regional corridor with a secretariat of its own. Seen narrowly, it is transport. Seen geoeconomically, it is a decision about the direction in which value flows, one that can strengthen a port, call logistics industries into being, draw in processing plants and redraw the commercial geography of several countries. So the question should not stop at who builds the line.
It should extend to who operates it and on what terms, since the Angolan line runs under a thirty-year concession held by a consortium led by a commodities trader, and above all to what economic system the line enables. A railway that carries copper from a mine to an overseas port makes extraction more efficient. A railway that binds mines to power, processing, industrial clusters, regional markets and ports can help form an industrial economy. The first moves commodities. The second can move an economy.
The Morality Play and the Real Contest
The renewed competition over Africa is usually narrated as China against the West. The frame is too crude for what is happening. China’s position across African infrastructure, mining, manufacturing and trade grew out of years of commercial engagement, and its strategic weight is partly the accumulated weight of those relationships. Western governments now attend more closely to critical minerals, supply-chain resilience and infrastructure because the strategic importance of these systems has become impossible to ignore.
Neither development is a morality play. States pursue interests, companies pursue returns, governments protect strategic industries, and supply chains become instruments of national security when their disruption threatens essential industries. That is geoeconomics in its plainest form: commercial relationships turn strategic when what is traded becomes indispensable.
The scale is now measurable. UNCTAD reports that since 2020 governments have introduced nearly 100 export-related measures on critical minerals, and it counts 73 international agreements and partnership instruments in the field, 58 of them signed after 2022. The significance lies beyond the individual instruments. Governments have begun to treat supply chains themselves as strategic assets.
That opens a door for Africa and sets a trap. The trap is a quieter stereotype than the others: the habit of speaking of “Africa” as though fifty-four states were a single seller. They are not. If they compete one by one for external capital by offering ever more generous concessions, the continent’s strategic importance will dissolve into a race to the bottom. If they instead use the rivalry among external powers to bargain for technology, skills, processing capacity, infrastructure and market access, the same rivalry becomes a source of strength.
The difference lies in African strategy, and there is evidence that African governments can act on it. When cobalt prices collapsed in 2025, the DRC suspended exports and then introduced annual export quotas, which its president said would raise prices and support the national economy. One may doubt the wisdom of the policy. It is still not the conduct of a passive object of other people’s strategies.
What Investment Actually Buys
African political conversation swings between two lazy positions: that external interest is inherently suspect, and that foreign investment is inherently good. Both spare their holders the labour of analysis. Foreign capital can finance infrastructure, transfer skills, create employment, open markets and accelerate industrial development. It can also produce enclaves, repatriate profits, deepen dependence, weaken domestic suppliers or leave almost no productive capability behind.
What matters is the structure of the investment and what that structure produces. A mine that employs people but imports nearly everything it needs, ships an unprocessed commodity and leaves little capability behind has a different developmental effect from one tied to local suppliers, technical training, processing, research and manufacturing.
This is why headline figures tell us so little. UNCTAD’s World Investment Report 2026 puts foreign direct investment into Africa at about $70 billion in 2025, the third-highest level since 1990, and notes that the benefits remain concentrated in a limited number of countries and sectors. An auditor looks inside the number. What knowledge enters the country, and what skills remain when the project ends?
Which local firms emerge and which are displaced? What infrastructure becomes available to others, and what technology is transferred, on what terms? What tax revenue is captured, what environmental liabilities remain, and what happens when commodity prices fall? And what bargaining power does the host country hold when the contract comes up for renewal? The development question is shifting from the attraction of investment to the design of investment. That is a harder conversation, and it is the necessary one.
The Warning Inside the Opportunity
Here lies the contradiction of the moment. Africa may become more indispensable to the global economy without becoming industrialised enough to exploit that position. It can be essential to the world’s energy transition while millions of its people live with unreliable electricity. It can supply the minerals for advanced technologies while importing much of the technology needed to process them. It can hold extraordinary renewable-energy potential and lack the transmission systems that industry requires, and it can contain one of the world’s largest future consumer markets while depending on imported manufactures to serve the present one. This is an argument against complacency, not a case for pessimism.
The African Development Bank’s 2025 Industrialisation Index puts numbers to the gap. Manufacturing value added rose from about $285 billion in 2020 to $351 billion in 2025, yet the continent still accounts for less than 2 percent of global manufacturing output and about 1.4 percent of global manufactured exports. Manufacturing value added per person, at $226.7 in 2025, remains below its 2014 peak of $254.9, which means that growth in the aggregate has not yet become structural change.
Intra-African trade, at 14.4 percent of the continent’s total trade between 2022 and 2024, compares with roughly 60 percent in Asia and 57 percent in Europe. The problem is not the absence of industrial activity. It is the mismatch between endowment and productive capacity, and the mineral opportunity will prove exactly as transformative as the productive system built around it.
Nigeria has particular reason to read this with caution. Its oil history holds both the promise and the danger of strategic abundance. Oil made Nigeria globally important, generated enormous revenue, drew foreign investment and placed the country at the centre of international energy politics. It did not, by itself, produce broad industrial capability. The lesson is not to search for the next resource that foreigners desperately want.
It is to build the capabilities that let Nigeria decide what happens after a resource is found: dependable electricity, competitive logistics, technical education, industrial finance, research capacity, local suppliers, regional markets, predictable regulation, and firms able to move from contracting to ownership, from extraction to processing, and from processing to innovation.
Nigeria’s large domestic market is an advantage many resource economies lack, and the African Continental Free Trade Area could extend it by treating the continent as one system of production and consumption. That will remain theoretical while African economies trade more readily with the outside world than with one another. The continent does not need to be self-sufficient. It needs to be connected enough to manufacture at scale, which is a different ambition.
Productive Sovereignty
“Resource sovereignty” is an attractive phrase and an incomplete one. A country can control its natural resources in law while lacking the technology, capital, infrastructure and industrial base to transform them competitively. What Africa requires is productive sovereignty: enough technological, industrial, financial and institutional capability to take part meaningfully in the value chains that matter to its future. It does not mean producing everything at home, which no modern economy does.
The distinction changes how governments should weigh foreign investment. The test is not how much money a project will bring, but what capability it will help the country acquire. Processing technology, engineering skill, logistics infrastructure, local suppliers, research partnerships, intellectual property, managerial competence and access to regional markets are the currency worth negotiating for. The point is not to reject globalisation but to bargain with it intelligently. UNCTAD’s investment analysis reaches a similar conclusion, treating the broadening of investment’s development impact, through supplier development, better logistics and energy, and regional integration, as the central challenge.
Here the second scramble differs most from the first. The first was imposed largely upon Africa. The second is being negotiated with African governments and institutions. That gives Africa more agency, but agency is only useful when it is exercised with competence.
The Danger of Being Wanted
There is an irony in Africa’s new visibility. For decades African leaders complained that the world ignored the continent. Now mineral companies, technology firms, governments, development institutions, manufacturers and investors are all interested. The psychological temptation is to read that attention as proof of power. It is not. Being wanted is not the same as being powerful. A country becomes powerful when it can convert what others need into outcomes it values, and that requires bargaining capacity, which comes from alternatives.
If Africa has one buyer, one financier, one technology provider, one transport route and one processing destination, its geological abundance may buy surprisingly little. If it has many buyers, competing sources of finance, rival infrastructure routes, regional processing capability, skilled labour, domestic capital and integrated markets, its position changes. The objective is therefore not to choose the right external power. It is to become capable enough that no external power is indispensable to Africa’s own strategy. That is the essence of geoeconomic maturity.
The Question That Remains
The signs that the second scramble is under way are no longer hard to read. States are securing critical-mineral relationships and restricting exports. Corridors are acquiring strategic weight, processing capacity has become a geopolitical asset, industrial policy has returned, and supply-chain security now forms part of national security. Africa’s minerals sit near the centre of these calculations, and the outcome remains open.
The continent could use the moment to accelerate industrialisation, build regional production networks and processing capacity, deepen its energy systems, strengthen African firms and convert strategic resources into lasting productive capability. Or it could reproduce the older pattern in a more sophisticated form: foreign capital enters, resources leave, infrastructure is built around extraction, value is captured elsewhere, and Africa congratulates itself on the volume of investment attracted. Geology will not make that choice. Institutions, leadership, bargaining, capability and strategy will.
The real prize sits neither in the mine nor in the port, neither in the railway nor in the refinery nor in the foreign investor, but in the system that connects them: the technology, capital, energy, skills, manufacturing, logistics, markets and intellectual property that turn a resource into durable economic power.
For once, the world may need Africa not merely because the continent is large, populous or well placed, but because some of the materials and capabilities required for the next global economic order are concentrated here. History has already taught a hard lesson about what that is worth by itself. A resource can make a territory valuable without making its people powerful. The second scramble will test whether Africa has learned the difference.
The question is African in its particulars and global in its reach, since the same test awaits every society that suddenly finds itself needed. The great African question of the coming decades may therefore be neither who wants our minerals nor who is investing in Africa. It is more fundamental. Can Africa turn what the world needs into what Africa itself is capable of becoming? That is where the second scramble will ultimately be decided.
**This is the first of my18 layered adventure along the “geoeconomic insight of Africa” readers are encouraged to share their perspectives.
Charles is a global geoeconomic analyst and contrarian thinker